The £1,000 Question: Payday Advert or Credit Union Loan?
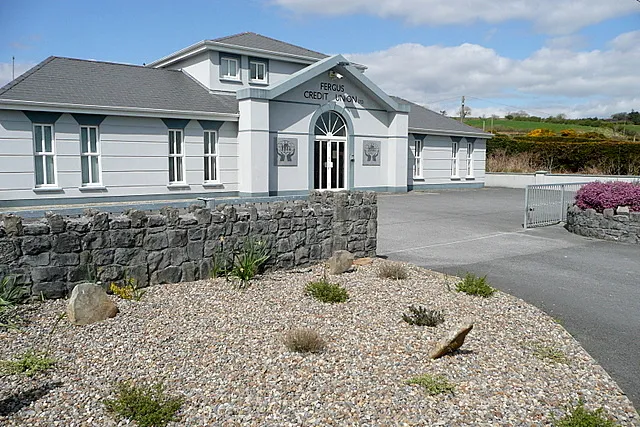
Photo: Graham Horn , CC BY-SA 2.0, via Wikimedia Commons
Payday adverts have a certain confidence about them. Big numbers, bright buttons, money in minutes. Credit unions, by contrast, tend to advertise like a library noticeboard: useful, worthy, and easy to walk past. But if you need £1,000 in a hurry, the quieter option deserves at least a look before you tap “apply” on a high-cost short-term loan.
This is not a pitch. Credit unions are not a magic fix, they are not available to everyone, and they are not always the cheapest route once you factor in time and membership rules. But in a lot of UK households, they are the borrowing option that never gets checked. So let’s check it properly.
What a credit union actually is
A credit union is a financial co-operative. It is owned by its members, not shareholders, and it usually serves people who share a “common bond” — living in a certain area, working for a particular employer, or belonging to a specific trade or community group. Some are open to anyone in a region; others are much narrower.
They offer savings accounts and loans. Many are small, run by volunteers and part-time staff, and regulated by the Financial Conduct Authority and Prudential Regulation Authority. They are not dodgy. They are just not built for the pace of a payday advert.
The membership bit nobody mentions in the advert
Before you can borrow from most credit unions, you usually need to become a member. That often means:
- checking you fit the common bond;
- opening a savings account;
- paying in a small regular amount, sometimes for a set period before a loan is considered;
- and accepting that decisions may take days rather than minutes.
Some credit unions will lend to newer members. Others want to see a savings habit first. That can be a genuine barrier if the boiler has just died and you need money this week. It is also the reason credit unions tend to attract people who can plan a little, rather than people in a full-blown emergency.
So the first honest question is not “are credit unions cheaper?” It is “can I actually join one in time?”
A realistic £1,000 comparison
Let’s use a straightforward example. You need £1,000 and you can repay it over 12 months.
A credit union loan might be priced at up to 42.6% APR, which is the current maximum for many credit union loans in the UK. Some charge less. On a £1,000 loan over 12 months at 42.6% APR, you might repay roughly £102 a month, with a total cost of around £1,225. That is not cheap in absolute terms, but it is predictable.
Now compare a payday-style loan. A typical high-cost short-term credit product might charge 0.8% per day, with default fees on top. If you borrowed £1,000 for 90 days, the interest alone could be around £720 before fees, subject to the total cost cap. In other words, a three-month payday loan can cost more than a year-long credit union loan — even though the credit union term is longer.
That is the boring advantage. The credit union loan is not exciting. It just tends to spread the cost over a sensible period rather than asking you to clear a huge chunk on your next payday.
But compare carefully. If you only need £300 for two weeks, a credit union may not be practical or cheap enough to bother with. If you need £1,000 for a year, the maths changes.
Where credit unions can lose
Credit unions are not automatically better. They can lose on:
- Speed. You may wait days or weeks for membership and loan assessment.
- Access. Not everyone lives or works in a qualifying common bond.
- Savings rules. Some require you to save before you borrow, which is hard when money is already tight.
- Loan limits. Some have lower maximum loans, especially for newer members.
- Online experience. Some are friendly on the phone but clunky on the website.
- Convenience. A payday lender will often decide in minutes. A credit union may want paperwork.
If your situation is urgent and you cannot wait, a credit union may simply not be the right tool. That is not a moral failure. It is a timing problem.
Affordability checks: different flavour, same principle
Credit unions still have to check that you can afford the loan. They are not looser than mainstream lenders in any meaningful sense. They may look at your income, outgoings, credit file and existing debts. Some will ask for bank statements. Some will want to know why you need the money.
The difference is tone. A credit union may be more willing to look at your whole situation rather than a score alone. But it will still say no if the numbers do not work. Do not join a credit union assuming it is a guaranteed yes.
Questions to ask before you join
Before you fill in a membership form, ask:
- Do I qualify under the common bond?
- How long does membership need to be open before I can apply for a loan?
- Do I have to save regularly, and how much?
- What is the maximum loan for a new member?
- What APR will I actually be charged, not just the headline rate?
- Are there arrangement fees, early repayment charges or penalties?
- What happens if I miss a payment — and will they talk to me before it becomes a problem?
Those questions take ten minutes. They can save you a lot more than ten minutes’ worth of regret.
The boring verdict
A credit union loan is not the answer for every borrowing crisis. It is slower, fussier and less universal than the payday advert. But for a £1,000 loan you can repay over several months, it is absolutely worth checking before you commit to high-cost short-term credit.
The boring option might not have the best advert. It might just have the better ending.